Insights
The Curious Investor - China Shock 2.0: From the Inside
The Curious Investor is back. After a short absence and a very interesting trip abroad, Jeremy McKeown returns with a first hand view of China’s scale, its deflationary force and why “China Shock 2.0” matters to investors.
China Shock 2.0: From the Inside
I visited China last month, curious to see inside the country many consider the West’s economic and geopolitical bogeyman. I wanted to see how things had changed since I was last there forty years ago.
1986 was an exciting year for a young City professional looking forward to the Big Bang deregulation of the London stock market. Meanwhile, China was undergoing a more profound, albeit cautiously managed, change, which Deng Xiaoping, its architect, likened to “crossing the river by feeling the stones”.
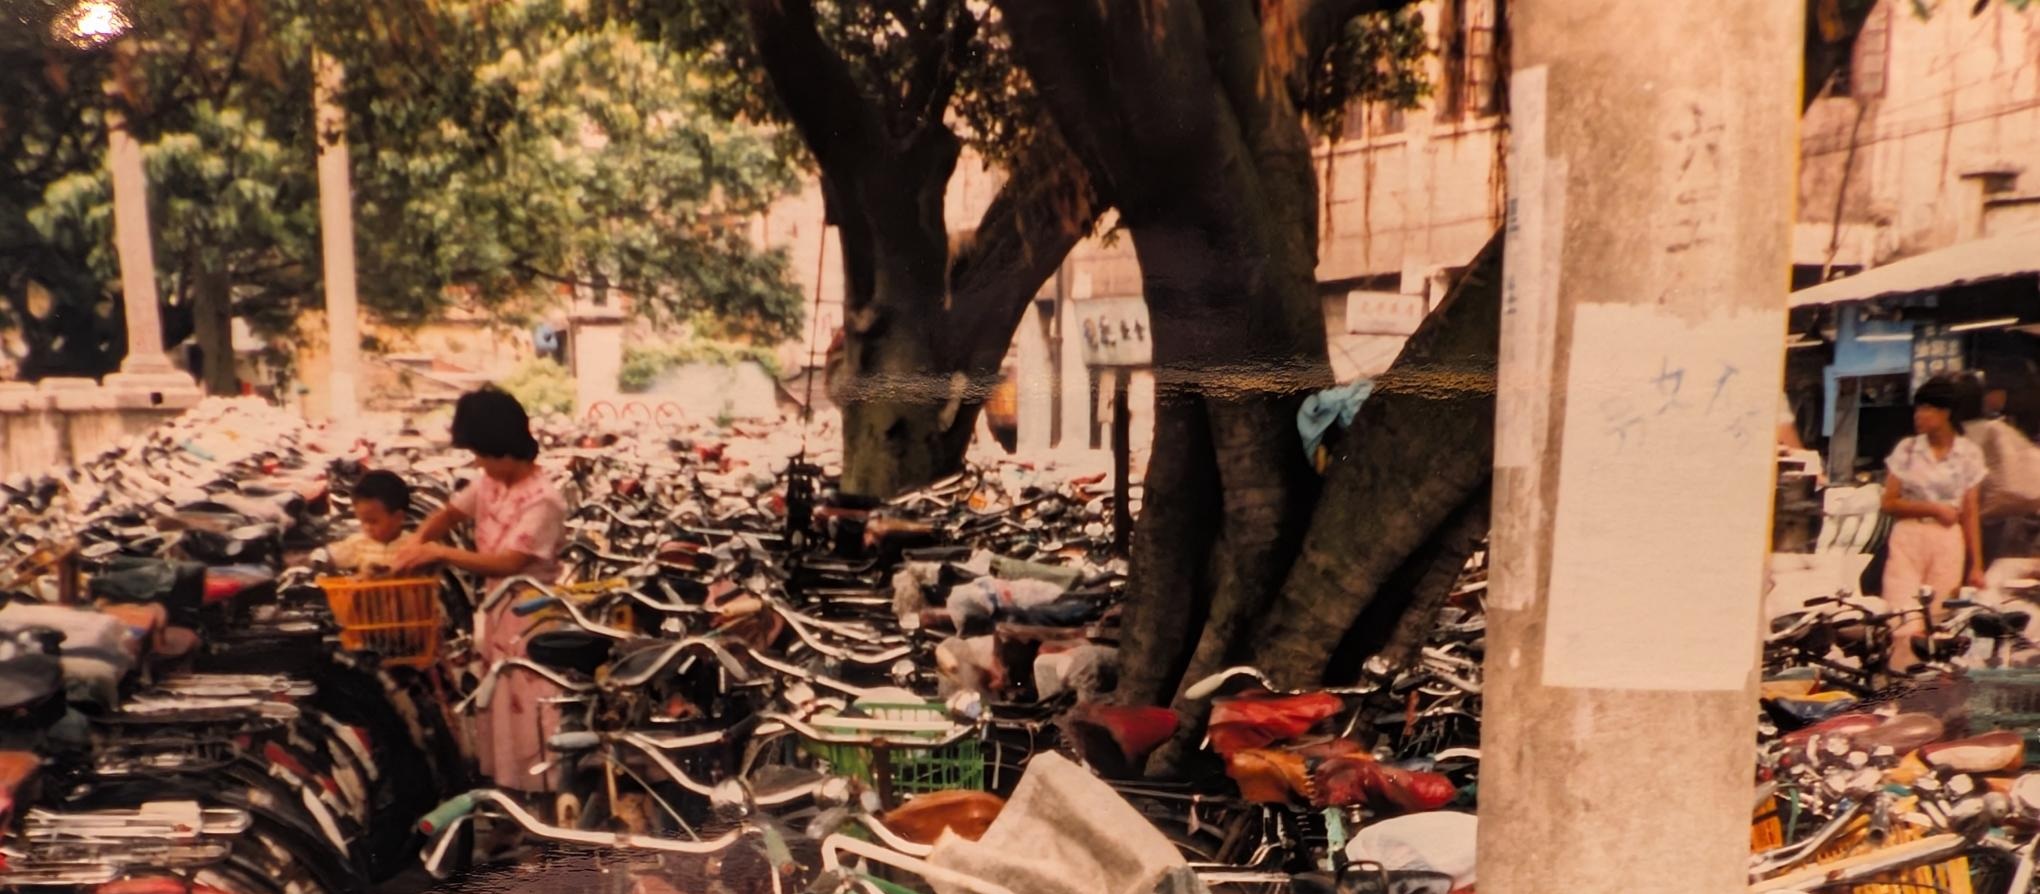
The country was opening up. Foreigners could visit without an official tour guide, though a visa was required and available only in Hong Kong. Once there, most people, particularly outside the major cities, wore simple Mao-style clothing, rode bicycles and stared at strangers. I remember the food as being inedible.
How things have changed.
In those days, China’s economy was roughly half the size of Britain’s; today it is about five times larger. While the UK’s average earnings have doubled in the intervening period - albeit not at all since 2008 - China’s have risen fifteen fold.
Following its admission to the WTO in 2001, China became the world’s low-cost workshop. Today, it is an unparalleled global manufacturing and export powerhouse.
In 1986, most people thought China was simply a potential source of cheap products. Today, Western politicians and the media portray China as a geopolitical and economic rival, citing “China Shock 2.0” as a force destabilising industries and distorting global trade. Much the same was said about Japan in the 1980s.
A trip planned by AI
I had wanted to revisit China for a while. On 12 July this year, I typed the following into a Claude Cowork context window, and the trip came to life on my screen:
“Draft an outline itinerary for a two-week visit to China for October 2026, including costings and options. Ask User Questions.”
After a month of iteration and updates, I had a fully booked itinerary complete with every destination, hotels, long-haul flights, domestic high-speed train and ferry reservations, plus full instructions on money, payment apps, eSIM cards and electric socket types.
There was along list of restaurant suggestions and places to visit each day; something a travel agent would once have charged a significant fee to provide. When we landed in Shanghai, we knew exactly how to get to the hotel and which part of town to head to in order to fend off the jet lag.
After enjoying the tree-lined streets of the French Concession for a few hours, we needed to eat. We stopped at a busy neon-lit noodle stall with plastic tables and chairs, navigated the WeChat menu, and ordered and paid through the app, easily connected to a Wise account denominated in yuan.
We were soon served a large dish of freshly cooked dumplings, a bowl of egg noodles, a large plate of steamed vegetables and two beers. There was plenty, and it was just what we needed. The Wise app showed the bill came to £7.04.
More beers were then ordered. How could you not at those prices?
China’s deflationary economy
This was our first taste of China’s deflation, which also shows up in travel costs.
Most journeys on the Shanghai Metro cost about 30p. Line 11, its longest, runs 84km, and you can travel its entire length for less than £1; the carriages and stations are spotless.
Our longest travel day was the 500km from Guilin to Guangzhou. Door to door, it took less than five hours, involving two 45-minute cab rides - Didi is China’s Uber, but better and a fraction of the cost - and two first-class train tickets. Comfort all the way, travelling effortlessly at 350km per hour, the all-in cost for the day’s journey was £77. Had we travelled second class, it would have cost £55.
But cars are where China’s productive prowess is most obvious, and potentially most deflationary on a global scale. On the streets, the thousands of old-school bicycles of forty years ago are gone; everyone without a car travels by electric scooter, while EVs are increasingly prevalent in the larger cities.
China has well over a hundred car manufacturers, and most of the cars on the road are makes and models unknown in Europe. But they are heading our way soon.
While we were there, an EU trade delegation was in Shanghai agreeing terms intended to limit imports of Chinese hybrids to 350,000 a year, as part of a broader trade agreement.
Cars are just one visible aspect of China’s huge and growing trade surplus, which is creating significant challenges for Europe’s manufacturing industries. Over the first nine months of 2026, China’s trade surplus totalled $938.1 billion, up from $875.1 billion a year earlier, putting 2026 on course to beat last year’s $1.2 trillion record.
These extraordinary numbers equate to about 1% of world GDP. Roughly what America ran during the Second World War, relative to the world economy.
The first China shock sent toys and textiles west and German machine tools east; Europe, mainly Germany, did well out of it. The second shock is sending low-cost cars, solar panels and machinery - things Europe makes.
China Shock 2.0 is underway, and this time it is coming for Europe.
Why China produces more than it consumes
A 16-night trip around southern China cannot uncover definitive insights into the nature of China’s manufacturing and export-led powerhouse, but I can offer a few thoughts.
China’s citizens are producers rather than consumers. They typically work six days a week. For many people, Saturday is a normal working day. Frequently, stallholders, shopkeepers and security guards were fast asleep, a testament to their long hours.
Day-to-day necessities are cheap, but most Chinese people cannot afford to travel by high-speed train. A ticket to the viewing platform atop Shanghai Tower was £25; a bottle of Sprite at the top was 70p.
The Chinese Communist Party might govern China, but it directs an economy with the force of full-throated capitalism. Crucially, though, it often does so without a market economy’s restriction of capital to unprofitable companies.
If China wants to dominate a market - EVs, for example - state and local authorities, together with their state-backed lenders, can create and support EV companies. Only about two or three of China’s car manufacturers are profitable. Its largest and most profitable, BYD, saw sales growth to the EU rise by 175% in the first nine months of this year, while its domestic sales fell by over 27%.
While many Western economies continue to face inflationary pressures, China is experiencing weaker domestic demand and deflationary pressures in parts of its economy. This, together with a strong savings culture, can make households more cautious about discretionary spending. With a less comprehensive social safety net than many Western economies, households also have a stronger incentive to save and build financial resilience for themselves and their families.
As Kristalina Georgieva neatly summed up global economic imbalances at the recent IMF meeting: “China needs to spend more, the US has to save more, and Europe has to invest more.”
What could China Shock 2.0 mean for investors?
China Shock 2.0 is not a reason to make an immediate investment decision, but it is an important structural shift to understand.
China's export capacity could keep putting downward pressure on prices in electric vehicles, batteries, solar equipment, industrial machinery and consumer goods. That is difficult for businesses competing head-on with Chinese manufacturers, many of them European carmakers and industrial firms. Equally, it can benefit businesses and consumers able to source cheaper components, equipment or finished goods, and lower goods prices may help ease inflation more broadly.
Rather than predicting the next headline, the more useful question is how resilient the companies you own are. For example:
- Which of my holdings face direct competition from lower-cost Chinese producers?
- Which could benefit from falling input costs or cheaper capital equipment?
- Do they have genuine pricing power, a differentiated product or a lasting cost advantage?
- Do any rely on selling into China, where domestic demand has been weaker?
- How exposed is my portfolio to tariffs, quotas or other changes in trade policy?
- Is my exposure to European industrials, autos or renewable-energy supply chains deliberate and understood?
These are sensible questions to discuss with your investment manager. The aim is to understand how a major shift in global manufacturing could affect margins, competitiveness and long-term returns, not to react to each development.
An extraordinary place to visit
As a Western consumer able to travel, China is an easy place to get to. With a UK passport, you do not currently need a visa for a short visit. Travelling around is easy with AI’s help and some unfamiliar apps, including Didi, Trip.com, Amap, Alipay and WeChat.
The food isgreat, and the prices are unbelievable. I hope to return before 2066!
IMPORTANT INFORMATION
This has been prepared by Dowgate Wealth Ltd for information purposes only. It reflects the author’s views at the date of publication and does not constitute investment advice, a personal recommendation, or an offer to buy or sell any investment. It does not take account of any recipient’s individual objectives, circumstances or needs; you should consider whether any investment is appropriate for you and, where appropriate, seek independent professional advice.
The views expressed are those of Dowgate Wealth Ltd at the date of publication, are subject to change without notice, and should not be relied upon as a guarantee of future events. Any forward-looking statements, forecasts or estimates are based on current assumptions, are subject to known and unknown risks, and are not reliable indicators of future performance. References to specific companies, securities, sectors or themes are illustrative only and are not recommendations.
Information has been obtained from sources believed reliable, but Dowgate Wealth Ltd does not guarantee its accuracy or completeness and accepts no liability for loss arising from reliance upon it, except where liability cannot be excluded under applicable law.
The value of investments and the income from them can fall as well as rise, and you may get back less than you invested. Your capital is at risk. Past performance is not a reliable indicator of future performance. Tax treatment depends on individual circumstances and may change.
Dowgate Wealth Ltd, registered in England number 12221221, is authorised and regulated by the Financial Conduct Authority and is a member of the London Stock Exchange. Registered address: 15 Fetter Lane, London, EC4A 1BW.
Written by
Jeremy McKeown